The insurance company has an adjuster. You should have one too.
We inspect your damage, document your claim, and negotiate with your insurer, so you are paid what your policy owes you. No upfront cost.
Renato Vallejo · Public Adjuster · FL License W632625
Free claim review
Talk to a licensed adjuster. No obligation.
(850) 544-9912 Call Now Text Us Email Us- Your insurance policy or company name
- Photos of the damage
- Any letter from your insurer
Property damage claims we handle
Residential and commercial, from first inspection to final settlement.
Roof damage
Storm, wind, and age-related damage to shingle, tile, and flat roofs, and the leaks that follow.
Hurricane & wind
Structural, roof, window, and water-intrusion damage from named storms.
Water damage
Burst pipes, appliance leaks, and sudden discharge, including hidden damage behind walls.
Fire & smoke
Structure, contents, and additional living expenses while you rebuild.
Mold
Mold resulting from a covered water loss.
Commercial & churches
Property claims for businesses, churches, schools, and associations.
Four steps. We handle the heavy lifting.
Free review
We inspect the property and read your policy, at no charge.
Document
Photos, measurements, and a line-by-line repair estimate.
Negotiate
We deal with the calls, letters, and paperwork with your insurer.
Settle
You approve the settlement. Our fee is a percentage of it.
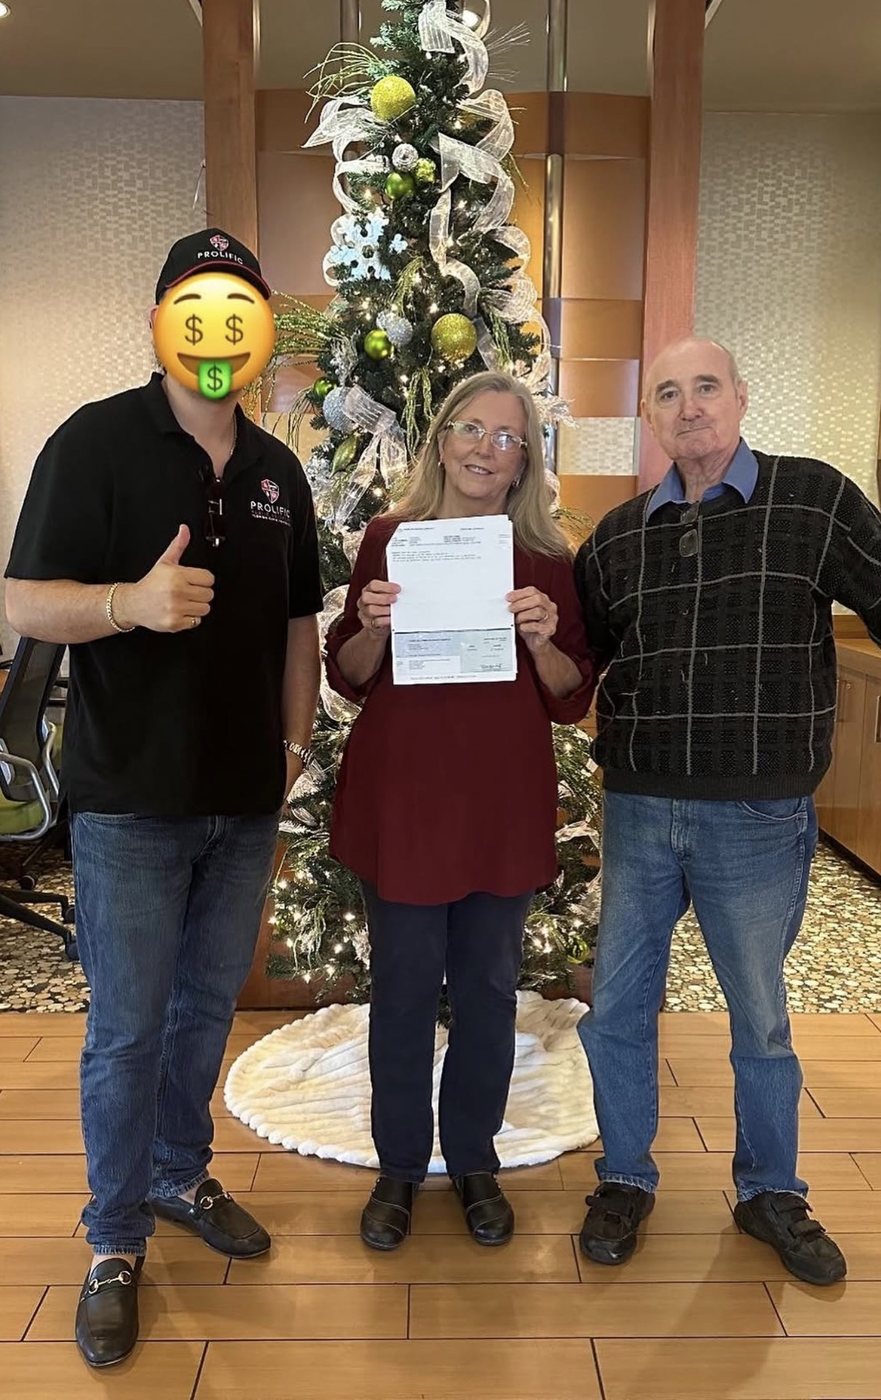
From below the deductible to a check in hand
Results vary and depend on the facts of each claim and the terms of each policy.
A licensed adjuster on your side
Prolific Public Adjusters represents policyholders only, never insurance companies. When you call, you reach the adjuster who will handle your claim from the first inspection to the final settlement.
Renato Vallejo · FL License W632625Common questions
What does a public adjuster do?
A public adjuster is licensed by the state to represent policyholders in an insurance claim. The insurer's adjuster works for the insurer. We work for you.
How much does it cost?
The review is free and there is no upfront cost. Our fee is a percentage of your settlement, as set out in your written contract and within the limits Florida law allows.
My claim was denied or underpaid. Is it too late?
Often not. Florida sets deadlines for reopening and supplementing claims, so contact us as soon as you can and we'll tell you where you stand.
Can you guarantee a higher settlement?
No one can honestly guarantee an outcome. What we can promise is a thorough inspection, a fully documented claim, and an adjuster who reads your policy.
Don't accept the first offer
Get a free, no-obligation review of your claim from a licensed Florida public adjuster.